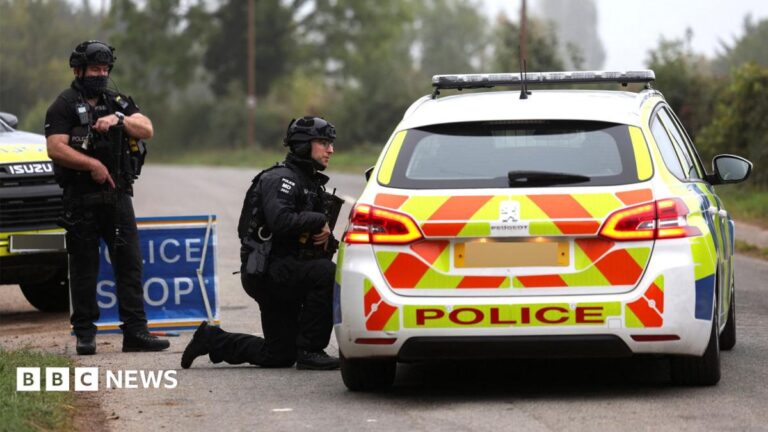


The Financial Conduct Authority (FCA) has targeted three London premises suspected of illegal peer-to-peer cryptocurrency trading in a joint operation with HM Revenue and Customs and the Metropolitan Police.
The City watchdog said on Thursday that it had issued three cease-and-desist letters to individuals trading through UK businesses, ordering them to stop the alleged illegal activity.
Authorities warn of money-laundering risks
Peer-to-peer trading allows people to buy and sell cryptocurrency directly with each other, bypassing centralised exchanges. No peer-to-peer crypto traders are currently registered with the FCA in the UK.
Authorities said unregistered peer-to-peer crypto traders can be used to move and launder illicit funds. They estimated that more than £100bn is laundered through UK corporate structures each year.
The FCA led its first formal crackdown on eight London premises suspected of peer-to-peer crypto trading in April. Evidence gathered during that operation has since supported several criminal investigations.
Steve Smart, the FCA’s executive director of enforcement and market oversight, said the regulator continues “to track and disrupt illegal crypto trading”. Detective sergeant Sathish Alalasundaram of the Metropolitan Police Service said the force continues “to evolve and adapt investigative capabilities and disruption tactics to bring those who break the law to justice”.
New crypto rules planned for October 2027
The FCA had previously drawn criticism for reversing its four-year ban on investors holding regulated crypto products last year.
In a briefing on Wednesday, the regulator outlined guidance stating that from October 2027, firms will need FCA approval to deal with British customers. Under current rules, crypto firms need only register with the regulator for anti-money-laundering checks.
Keith Grose, UK chief executive of Coinbase, told City AM that the new rules will “wipe out” firms unwilling to comply and raise consumer trust.
YouGov research commissioned by the FCA in December found that 25 per cent of cryptoasset users would be more likely to invest if crypto were better regulated in the UK. Roughly 8 per cent of UK adults currently hold cryptocurrency.
Home Office announces anti-money-laundering strategy
The Home Office’s anti-money-laundering and asset-recovery strategy includes 500 new officers to track dirty money, disrupt organised crime networks and seize criminal assets.
The strategy is backed by £500m of investment, with recruits to be spread across the police force, the National Crime Agency and the Crown Prosecution Service.
Related: FCA bans former Kingly Solicitors owner over £28m client money misuse
Source: City AM